

«Gold and silver are money. Everything else is credit.»
J. P. Morgan, before Congress, 1912
The old-economy trilogy, in order — Part 1 · Energy · Part 2 · Gold · Part 3 · The Miners
Gold.
A shiny yellow metal.
No cash flow. No dividend. No underlying business to value, no earnings to discount, no intrinsic worth we can calculate on a spreadsheet. By every rule of the quality-and-compounding investing we practise at arvy, gold should not interest us at all.
And yet here we are, writing about it for the second time — because in Part 1 of this trilogy we argued that the old economy is striking back, that the assets the last decade left for dead are quietly taking the baton. Energy was the cash engine. Gold is the memory — the asset that remembers every currency ever debased.
Let me be honest from the first line, the way I was when I last wrote about this: I am a gold bug. So take everything that follows with a grain of salt. You either believe in the ancient metal or you do not; there is very little in between.
But right now, we believe the stars are aligning. And the chart is screaming an opportunity that comes around once every several years.
The Oldest Cycle Ever Recorded
First, the fascination — because gold is not just an asset, it is history you can hold.
Gold was the first official medium of international exchange, introduced around 1,500 BC by ancient Egypt: the Shekel, a coin of about eleven grams, whose name simply means «weight». Think about what that word tells you. The very first unit of money was not a promise, not a number in a ledger, not the «full faith and credit» of anyone — it was a weight of metal you could hold in your hand. Money began as a physical thing, and gold was the thing.
Ever since, gold has outlived the rise and fall of every empire, watched currencies appear and vanish, and remained — stubbornly, uselessly, eternally — money. The Roman denarius, the Byzantine solidus, the gold standard of the British Empire, Bretton Woods: every monetary system in history has either been anchored to gold or eventually collapsed in its absence. Paper currencies have a mortality rate of essentially 100% over long enough horizons. Gold’s is zero. That is not mysticism; it is the historical record.
The Egyptians gave us something else, too: the oldest market cycle ever recorded.
In Genesis 41, Pharaoh dreams of seven fat cows devoured by seven lean ones. Joseph reads it as prophecy — seven years of plenty, then seven years of famine. It is, as far as we know, the first written description of a financial cycle. And remarkably, gold has obeyed it for as long as we have had data: it moves in seven-to-eight-year cycles, long stretches of advance punctuated by major setbacks, then renewal.
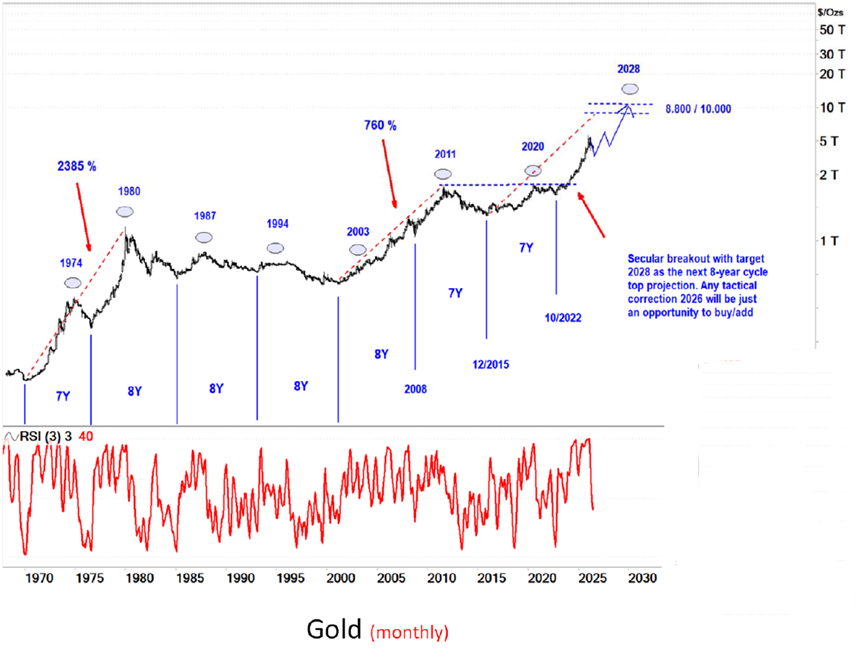
Chart 1: Gold, monthly — the seven-to-eight-year cycle, and the secular breakout pointing toward 2028.
Source: GMCP, Gold monthly — 7-8 year cycle, secular breakout
Look at the rhythm. Tops in 1980, 1987, 1994, the long base into 2000, then the great run to 2011, the consolidation into 2020 — each leg roughly seven or eight years apart. And then, from the 2022 low, a secular breakout to new all-time highs above the long base. If the cycle holds its 3,500-year habit, the projection points to the next major peak around 2028.
The Pharaoh’s astronomers, it seems, were also the first technical analysts.
And the cycle is not just shape — it is timing that has paid. Gold does its real work in the periods of monetary stress, and the numbers are striking. From 1976 to 1980, through the great inflation, the S&P 500 compounded at about 10.8% a year — and gold at 56.3%. From 2001 to 2011, across the bursting of the tech bubble and the financial crisis, the S&P managed roughly 2.4% a year while gold compounded at 20.6%. Gold spends long stretches doing nothing, and then, in the windows that matter most — when paper assets are failing and fear is general — it does almost everything. You are not paid to hold it most of the time. You are paid enormously to hold it some of the time, and you cannot know in advance which time.
The Honest Case Against
Now the part a gold bug is tempted to skip, and won’t — because we never sell only one side.
Gold’s long-run record as an investment is genuinely poor. Since 1800, after inflation, gold has returned roughly 0.6% per year — against about 3.3% for long Treasury bonds and 6.9% for US equities. Two hundred years of holding the shiny metal barely kept pace with the cost of storing it. It pays you nothing to wait, it generates nothing, and for long, brutal stretches — the entire 1980s and 1990s, the decade after 2011 — it does nothing but disappoint.
So let us be clear-eyed. Gold is not a compounder. It will never be the engine of a portfolio. Anyone who tells you it is the best long-term asset has not looked at two centuries of data.
So why, then, are we writing two thousand words about it?
Because gold is not bought for what it returns. It is bought for what it protects against. And the conditions it protects against have rarely looked more present than they do today.
Why the Stars Are Aligning
Strip away the romance and the case for gold now rests on a handful of structural forces, each one independent, all pointing the same way.
Debasement. This is the heart of it. Government debt has reached levels where the interest bill alone consumes an enormous share of output, and debt at that scale is rarely repaid honestly — it is inflated away. Lower real rates, yield-curve control, currency debasement: these are the tools, and gold is the oldest refuge from all of them. When the value of paper money is slowly, deliberately eroded to service the debt, gold is what holds.
Central banks are the buyers. This is the part most investors have not absorbed. The relentless bid under gold is not retail or speculation — it is central banks themselves, especially China and the emerging world, quietly rotating their reserves out of US Treasuries and into gold. And this is no longer a trend in the making: at the end of 2025, gold made up roughly 27% of global official reserves against about 22% for US Treasuries — the first time since 1996 that the world’s central banks held more gold than US government debt. The institutions that print the paper, and that built the dollar system, are themselves choosing the metal over the bond. Read that twice.
Supply cannot respond. Decades of underinvestment, almost no major new discoveries, declining ore grades, and permitting timelines that run ten to fifteen years mean that even a surge in the gold price cannot quickly bring new supply online. Structural scarcity, getting tighter.
Fragmentation. A de-globalizing, fracturing world favours the one asset that belongs to no government and depends on no counterparty. Gold is nobody’s liability.
And a twist most miss: the AI build-out is, for now, inflationary. The enormous physical effort of the AI era — the data centres, the power generation, the grid, the copper and steel and concrete — is a vast demand shock for real-world resources. Long before AI delivers whatever deflationary productivity miracle the bulls promise, it has to be built, and the building consumes hard assets and energy at a scale that pushes prices up, not down. The same force lifting the technology narrative is, underneath, quietly bidding for the very commodities that gold sits alongside. The asset-light story is being constructed out of an enormous pile of atoms.
None of these is a trading signal. Together they are the most durable macro backdrop gold has had in a generation — arguably more extreme than the 1970s or the 2000s, because the debt and the fiscal excess are larger now than at any point in the data.
Good Story, Good Chart — and a Gift
That is the «Good Story». Now the «Good Chart» — and this is where it gets timely.
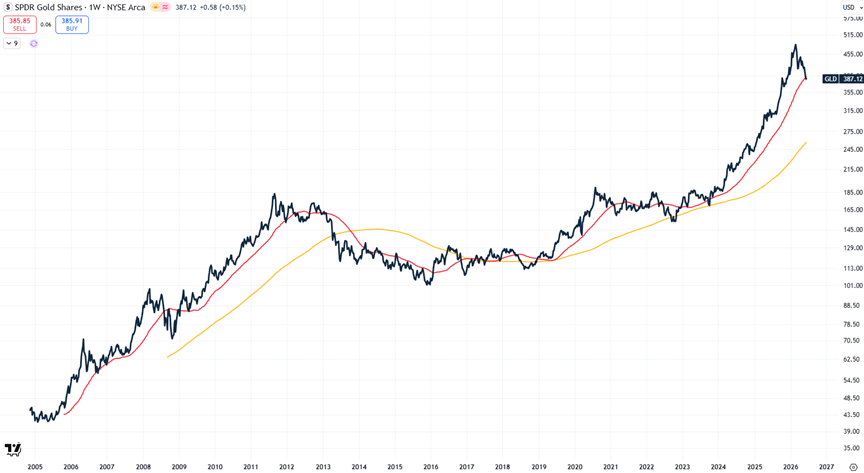
Chart 2: SPDR Gold Shares (GLD), weekly — the breakout, and the pullback to the rising trend.
Source: TradingView, GLD weekly — uptrend and pullback to the moving average
The long-term picture could hardly be more constructive: a powerful uptrend, a clean secular breakout, price riding above a rising trend. But — exactly as we described with energy in Part 1 — great breakouts do not run in a straight line. They pull back, they shake out the latecomers, and they hand the patient buyer an entry. And gold is doing precisely that right now.
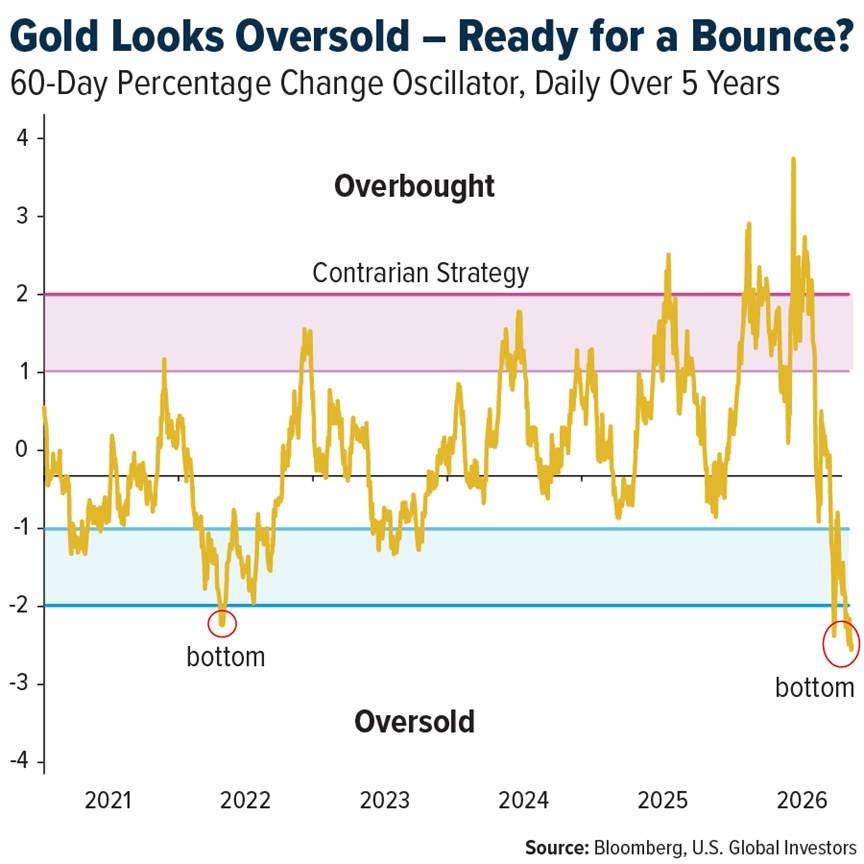
Chart 3: Gold’s momentum oscillator — deeply oversold, at levels that have marked prior bottoms.
Source: US Global Investors, Gold oversold — 60-day oscillator at bottom
Look at how stretched the selling has become. On a momentum basis, gold is now as oversold as it has been in years — pushed down into the zone that, the last several times, marked a bottom and a bounce. The trigger was mechanical, not fundamental: the nomination of a new Fed chair sparked a rapid repricing of rate expectations, a stronger dollar, and a violent bout of deleveraging that gave gold and silver their worst single sessions in decades. The carnage was concentrated in speculative, leveraged positions — not in the central-bank demand or the structural story. And gold rebounded quickly, doing exactly what a defensive asset is supposed to do. Sentiment, though, has completed a full round trip: a few months ago gold was everyone’s favourite trade; today it is almost completely forgotten. That shift — from crowded to forgotten, from overbought to deeply oversold, inside an intact secular bull — is the setup we wait for.
This is «be greedy when others are fearful», rendered as a chart. The story has never been stronger. The crowd has never been less interested. And the oscillator says the dip is here.
Buy the Dip — the Forgotten Trade
So here is the actionable view, stated plainly:
